Unlocking value
Reviewing the UK’s critical minerals midstream processing, recovery and recycling capability.
Dr Hollie Cockings CEng FIMMM (left) and Dr Dan Britton CSci MIMMM (right)
© Dr Hollie Cockings CEng FIMMM and Dr Dan Britton CSci MIMMMRising energy bills and empty supermarket shelves have starkly highlighted the impact of geopolitics on the security of supply of essential goods in the UK. As the transition to a low-carbon economy accelerates, critical minerals are emerging as the next strategic supply challenge. The future of the energy transition will depend not only on securing access to these minerals, but on the ability to convert them into economic value, industrial capability and resilient supply chains.
As the spotlight on critical minerals intensifies and demand is set to increase even more in the UK, we are open to vulnerability, being largely dependent on geographically concentrated global supply chains that sit within a fragile ecosystem. The UK Government has recognised this and has responded with the Vision 2035: Critical Minerals Strategy.
The strategy sets out an ambitious framework that aims to:
- Meet 10% of annual demand through domestic production (which includes extraction and primary processing and refining)
- Meet 20% of annual demand through recycling
- Ensure that no more than 60% of supply for any critical mineral comes from one country – a major measure of resilience
- Produce at least 50,000t of lithium domestically
The minerals challenge
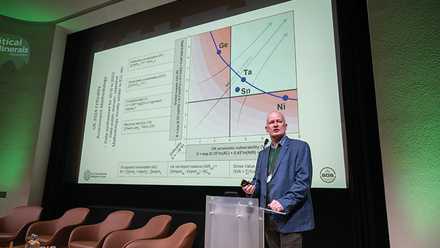
The Critical Minerals Intelligence Centre (CMIC) 2024 UK Criticality Assessment identified 34 critical minerals, including niobium, cobalt, lithium, rare-earth elements (REEs), platinum and even materials that we may consider abundant, such as aluminium, natural graphite and iron.
Although the UK has several emerging mining projects, a low reserve of naturally occurring minerals means that we remain heavily reliant on imported critical minerals. Furthermore, downstream operations such as processing, midstream and alternative production methods like recycling and recovery are also currently dominated by a small number of concentrated operators.
The risk of mineral shortages, disruption of supply and dependency on the global market, along with concentrated processing and mining supply chains, poses a risk to the UK’s economic stability and net-zero leadership ambitions.
Ore-pportunity knocks
Midstream processing represents the value addition point in the supply chain, where raw, extracted, or imported materials are processed to the point of being manufacturing ready.
When referring to solid, mined materials (as opposed to materials mined from geothermal waters), midstream processes include the extraction of minerals from their ores – from primary mineral processing to concentrates, through to smelting and refining, and later additive processes such as alloying.
An intrinsic link exists between midstream processing and recycling. Extractive processes are inherently similar to one another, given the parallel requirement to improve the purity of a material, no matter the source. In terms of capability, some operators will be able to refine ores and secondary materials such as mining waste, and process recycled materials such as black mass from batteries using the same technologies. Many therefore consider recycling as a midstream process. However, for this article, midstream processing/refining is specifically focused on primary feedstock such as ores and concentrates.
While our mining capability in the UK is limited compared to others, there is a pressing need to maximise the resources we do have. Research and exploration are underway, and the sector has also seen recent investment in known lithium and tungsten reserves, but substantial potential remains untapped and requires sustained effort and investment to realise it.
As well as the value in extraction, mining facilities are often paired with onsite processing, which acts as the first midstream process. Mining waste can also act as a feedstock for recovery, thus immediately unlocking further embodied midstream potential.
Currently, China’s midstream processing industry dominates, supplying almost all refined critical minerals. According to the International Energy Authority’s (IEA) Global Critical Minerals Outlook 2025, China is estimated to supply over 60% of the world’s refined lithium and cobalt and 80% of battery-grade graphite and REEs by 2035, as well as being the largest consumer and supplier of refined copper.
In terms of integrated midstream processing in the UK, some proposed mining sites have provided initial plans, suggesting primary onsite processing activities, but further plans for downstream processing are not as clearly documented. Where final-stage refining cannot be undertaken in the UK, material must be exported for processing overseas. This represents a missed opportunity to retain more value within the domestic supply chain and capture the economic benefits associated with downstream processing activities.
However, the UK has a well-established and successful extractive midstream processing industry concentrated on refining oxides and concentrates that are predominantly imported and on which it can build.
Of the midstream industries in the UK, there are exemplary cases that the sector can follow – Vale nickel refinery and Less Common Metals, to name a few. Both are active in supporting the procurement of oxides from sources outside of China where possible and have helped position the UK as a world leader in the refining of high-value materials. In addition, there are a number of other successful examples of critical minerals midstream processing activities, including the refining of platinum group metals (PGMs), lithium, REEs and magnesium.
The UK is clearly no stranger to midstream processing, with an extremely strong heritage and track record in refining and manufacturing, and many midstream processes were historically conceptualised and developed here.
The UK already demonstrates excellence through ongoing activities in the wider materials landscape, where it is considered a leader in the high-quality processing of key raw mined materials used in the construction, transportation and aerospace sectors. National strengths are also reported to be financing, insurance and consultancy, as well as high environmental, social and governance (ESG) standards, and excellence in research and education.
Reclaiming value from waste
Recycling and recovery represent an essential part of the UK’s strategy to secure critical mineral supply, as well as supporting the transition towards a low-carbon, circular economy.
The recycling and recovery stage is typically described as ‘downstream’ of the critical mineral lifecycle, where materials become available for reuse. An efficient recycling and recovery industry should take advantage of end-of-life, faulty and unused products, ensuring that as many critical minerals as possible are extracted and reused in the production of new materials. This is commonly referred to as urban mining.
The midstream provides the re-entry point for recycled materials, without which domestic recycling is restricted. To clarify, this article looks at recycling as the processing of end-of-life, faulty or unused products to allow the constituent parts to be separated and used for another purpose. Recovery refers to the processing of secondary waste and unused manufacturing materials, which also includes sources from historic mining processes.
Downstream recycling
The UK’s recycling capability includes both closed-loop recycling, which returns materials to similar-grade metal alloys, and open-loop recycling, which recovers critical minerals for use across different industries. Some processes also overlap with recovery, such as the capture and refinement of zinc from steelmaking dust. In terms of recycling feedstock, data from the British Geological Survey’s 2023 Minerals Yearbook shows that the UK exported large amounts of scrap between 2018 and 2022, more than 8Mt in the latter year.
Research from the University of Birmingham also found that approximately 80% of metal products in the UK that are classed as waste are exported, highlighting an enormous potential opportunity for a domestic supply of resource to be recycled.
Current UK recycling activity is primarily focused on established metal streams such as iron, steel and PGMs, alongside growing capability in lithium-ion battery processing and the recovery of aluminium, nickel and cobalt.
The UK is also actively scaling up REE recycling, with commercial facilities and projects emerging to recover permanent magnets from electric vehicles (EVs), wind turbines and electronic waste. However, many critical minerals are still not recycled at scale, and full domestic closed-loop recycling pathways remain underdeveloped for several materials.
Lithium-ion batteries are used in a wide range of technologies, from consumer electronics to EVs. At end-of-life, batteries are disassembled and shredded before being processed, either through pyrometallurgy (high-temperature treatment) or mechanical separation to produce black mass. In 2024, the Faraday Institute found that pyrometallurgical routes can recover cobalt, nickel and copper, but typically achieve lower lithium recovery rates and often result in graphite losses.
The report on Developing a UK lithium-ion recycling industry says that hydrometallurgical processing offers higher recovery rates and the potential to produce battery-grade materials, but commercial-scale capacity in the UK remains limited. Despite this, significant research and investment are underway to develop domestic capability and improve the recovery of high-purity critical minerals from spent batteries.
The UK currently has limited commercial-scale battery recycling and refining capacity, although several facilities are operational and additional projects are planned. Significant investments are being made to expand domestic capability, including Altilium’s proposed facilities, which aim to produce battery-grade materials and cathode active materials at commercial scale.
Platinum group metals, which include platinum and rhodium, are critical for auto catalysts, fuel cells, hydrogen technologies and specialist electronics. According to the UK Critical Minerals Association’s (CMA) report on Midstream Processing and Refining – Unlocking Security of Supply in 2024, eight sites were found to recycle PGMs within the UK, with no additional pilot or planned sites recorded.
The hydro- and pyrometallurgy processes often used in the recycling of PGMs are inherently similar to those used in the refinement of critical minerals. As such, the CMA report found that three additional sites in the UK also considered themselves as recyclers of PGMs, as well as midstream processers.
Permanent magnets, which are used in electronic devices, electric motors and wind turbines, represent the fastest-growing and most strategically important application for REEs, accounting for around 95% of total rare-earth consumption by value according to the IEA’s Global Critical Minerals Outlook 2025. It found that neodymium-iron-boron (NeFeB) magnets are most commonly used. However, other REEs in magnet technology include dysprosium, thulium, praseodymium and samarium.
Most recycling of REE material comes from electronic waste and EV components. A growing number of operational sites exist within the UK that can currently recycle REEs, with an additional site in pilot stage.
Iron has joined the CMIC critical minerals list due to the unsurprising demand for steel, largely associated with infrastructure and transportation. The steel industry is already considered a prevalent closed-loop recycler and is transitioning many of its UK plants from integrated blast furnace-basic oxygen steelmaking, which uses ~20% recycled ferrous content, to electric arc steelmaking, which frequently uses up to 100% recycled input.
However, it is important to consider that during electric arc steelmaking, the grades of steel produced are not the same specification or quality as the materials fed into the furnace, which means it still needs to undergo secondary processing or further alloying, often with critical minerals, to achieve the required product. As well as specific alloying elements, direct reduced iron can be added where speciality grades are required, which is also currently sourced from overseas.
The UK Government has taken British Steel into public ownership and also released its Steel Strategy – both actions aim to develop a sustainable, low-carbon future. The Steel Strategy focuses on capitalising on opportunities, such as using the nation’s abundant supplies of scrap steel and ensuring that public procurement projects are using home-produced steel.
Recovery – secondary waste and industrial by-products
Research shows that the UK’s legacy mine tailings constitute a significant but under-used secondary resource that contain REEs, cobalt, nickel, zinc and other critical or high-value by-product metals. Reprocessing these materials supports both supply security and sustainability goals by reducing the environmental risks of long-standing waste deposits, while recovering minerals that were either technologically inaccessible or commercially unimportant during historic mining.
Pilot studies, such as detailed geometallurgical assessments in the North Pennine Orefield, demonstrate that modern analytical techniques can detect nanoscale enrichments of critical elements, suggesting that modern extraction technologies could unlock material trapped in tailings.
Although the total national opportunity has not yet been fully quantified, research and recent investment suggests that individual sites may contain significant quantities of recoverable metals, with high companionality, indicating strong potential for locating
critical minerals.
Beyond mine tailings, metallurgical by-products – such as steelmaking slags, furnace dusts, manufacturing swarf and decades of accumulated fly ash – also represent valuable secondary sources of critical minerals. Various studies and projects across the UK and Europe have demonstrated the viability of recovering these materials through techniques such as bio-leaching, high-temperature processing and advanced chemical separation.
Barriers and recommendations
The UK critical minerals sector continues to face several structural challenges, including high energy costs, limited access to finance, skills shortages, lengthy permitting processes, weak domestic demand, fragmented supply chains, and difficulties securing reliable waste streams for recycling and recovery. However, there are significant opportunities to strengthen the UK’s position across the value chain.
Key priorities include expanding domestic processing and refining capacity, integrating recycled and secondary feedstocks into operations, and leveraging industrial clusters and freeports to create globally competitive hubs for critical minerals activity.
There is also growing potential to scale battery recycling, recover materials from renewable energy infrastructure and industrial by-products, improve electronic waste recycling, and strengthen circular economy approaches through better product design, traceability and end-of-life management.
Momentum is already building, with many of these priorities reflected in the government’s Vision 2035: Critical Minerals Strategy.
The strategy aims to unlock investment, strengthen international partnerships, support innovation, improve planning and permitting, and build a more resilient and competitive critical minerals industry. This is also being supported through the government’s £50mln programme for critical minerals projects and the Critical Minerals Accelerator, which is helping UK companies strengthen capabilities in areas such as midstream processing and recycling.
With renewed interest in the UK’s mining sector, there is an opportunity to expand domestic mineral processing and refining capabilities. Stakeholder engagement and existing recycling infrastructure suggest that processing facilities could diversify to handle a wider range of minerals, supporting efforts to develop more resilient supply chains.
Building on our established midstream industry, manufacturing heritage, financial sector and growing clean energy capabilities, the UK is well placed to grow a competitive processing sector serving both domestic and international markets.
The UK’s significant recycling and recovery feedstock potential also presents opportunities for circular economy development and industrial decarbonisation. Realising this potential will require clearer regulation, secure access to waste streams, design-for-recycling practices, and measures to retain critical-mineral-rich waste within the UK. Stronger collaboration between recyclers, manufacturers and government will be essential to support the growth of a robust domestic recycling and recovery sector.
While challenges remain, the UK has a significant opportunity to transform critical minerals from a strategic vulnerability into a source of industrial strength. With the right investment, policy support and collaboration, it can maximise value from domestic resources and build a globally competitive ecosystem that spans mining, processing, refining, recycling and recovery.
This article summarises key findings from the UK Critical Minerals Recycling and Midstream Processing Capability Assessment, commissioned by the UK Department for Business and Trade (now the Department for Business, Innovation, Science and Trade), and delivered by Frazer-Nash Consultancy in partnership with the Critical Minerals Association and the Materials Processing Institute, to inform the Vision 2035: Critical Minerals Strategy. The assessment was published in March 2025 and all information was verified as correct at this time.